Health Insurance
We focus on excellent customer service through client education and empowerment.
ThruCore will guide you through the process of finding quality health insurance that suits your needs. This service comes at no cost to you. Qualifying for coverage is only one part of the equation.
Understanding how to access and use the benefits is the other. We don’t just show you what to do, we educate you so you can do it yourself.
During your FREE initial consultation, we’ll go over your circumstances, your needs, and your budget, to find options that will work for you.
Do you know Your Numbers?
Know your income bracket to qualify for health Subsidization.
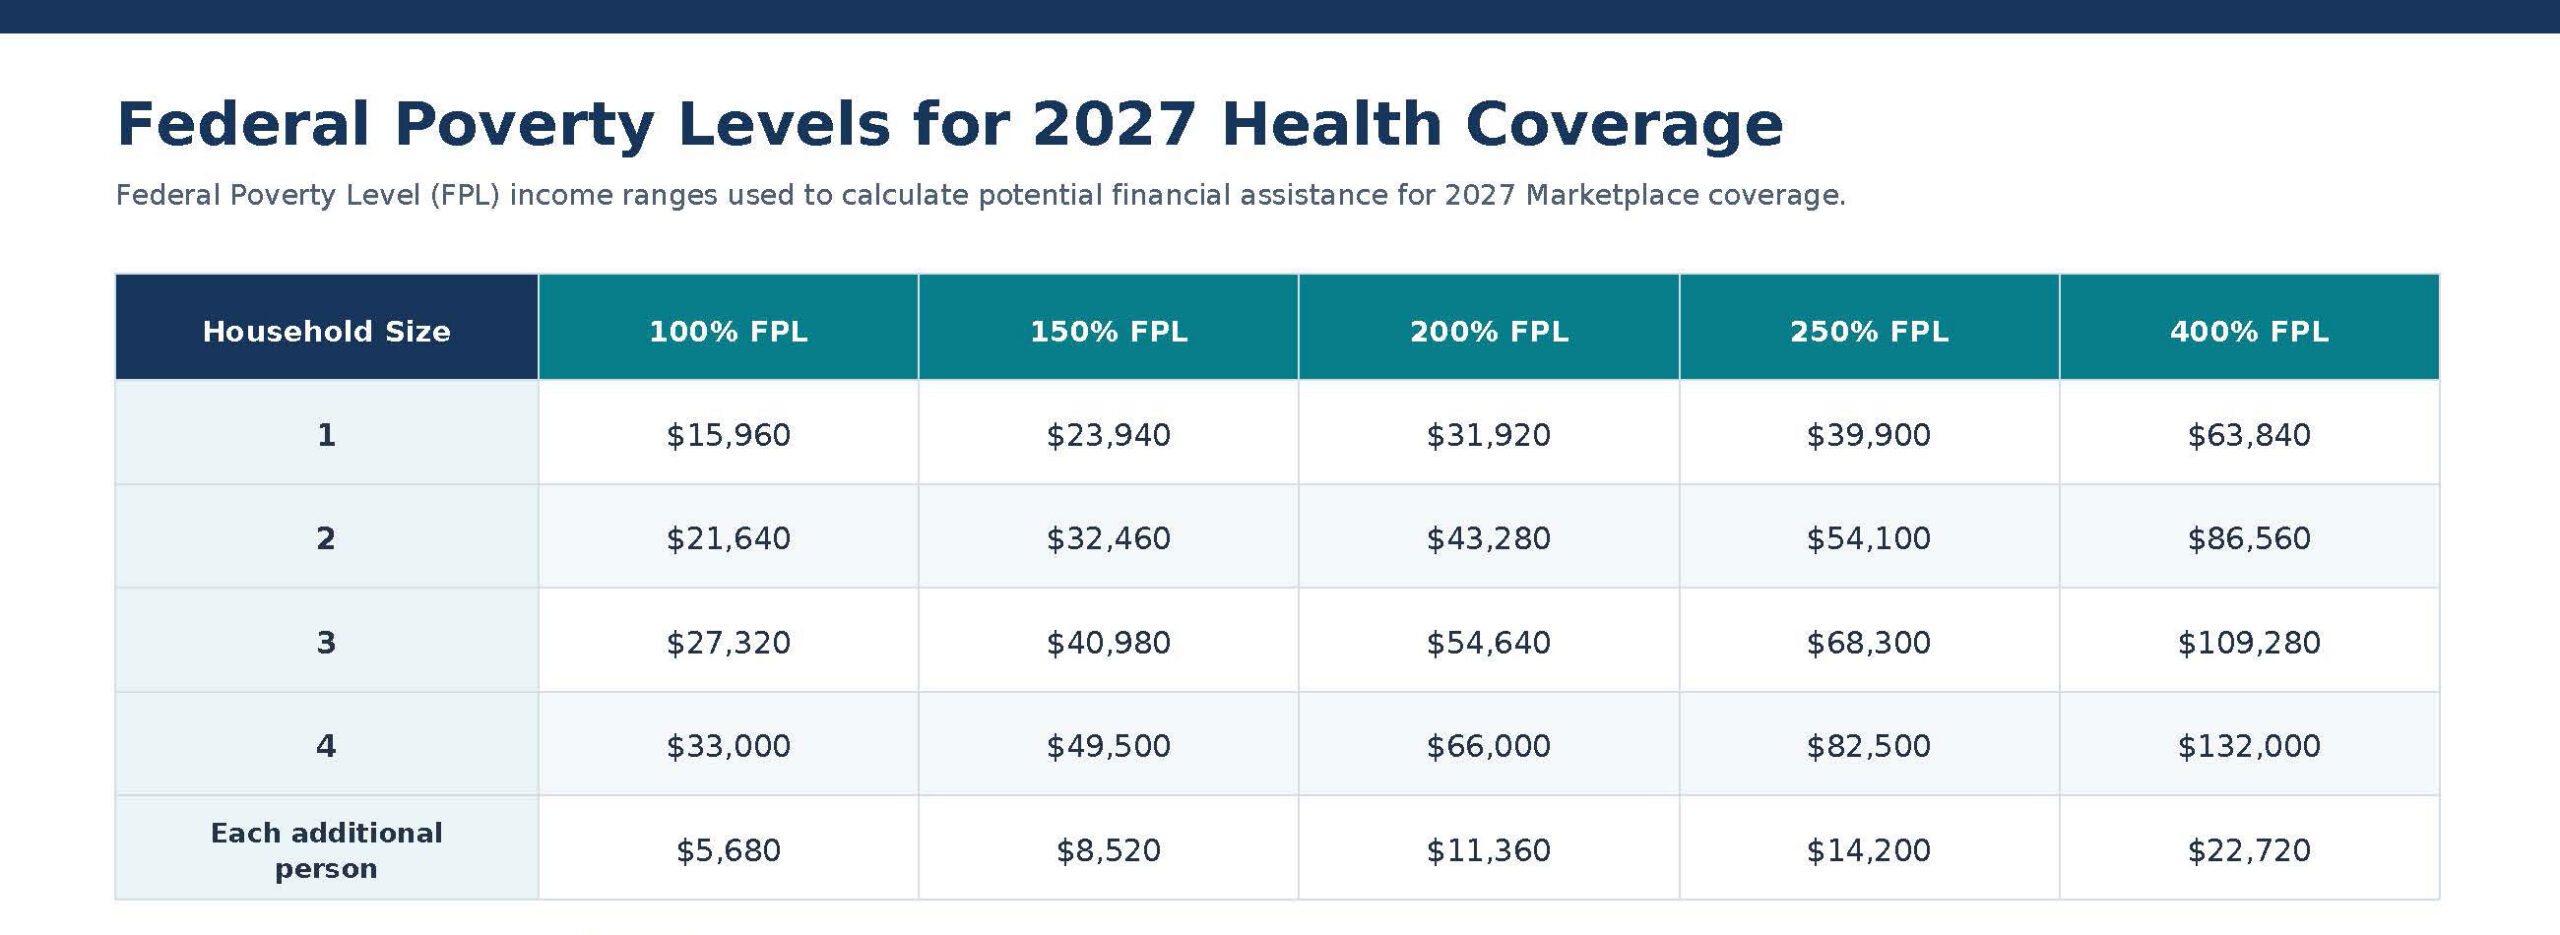
Help for paying your premium depends on your household income compared to the federal poverty guidelines. For 2027 coverage, the Marketplace uses the 2026 guidelines below (48 contiguous states, including Florida).
Important coverage and eligibility notes
- Florida did not expand Medicaid. Therefore, tax credits may be available as listed above for people with incomes above 100% of FPL.
- Household incomes below 100% FPL do not qualify for federal financial assistance to obtain health insurance coverage.
- Household incomes above 100% FPL may qualify for Advance Premium Tax Credits to offset premium costs.
- Household incomes between 100 – 250% FPL may also qualify for Silver with Cost-Sharing Reductions (lower out-of-pocket costs).
- Access to Silver Cost Share Reduction plans is not affected by federal decisions to fund the Cost Share Reduction program.
- Applicant cannot be enrolled in or eligible for government sponsored Minimum Essential Coverage (e.g. certain Medicaid or Medicare).
- Applicants eligible for employer group health coverage as either an employee or dependent may qualify for financial assistance to obtain Marketplace coverage if the group plan is not affordable or does not meet Minimum Value requirements. As of 2023, affordability for employer group health coverage is determined for both employee self-only coverage and family coverage using the same annual percentage of household income. For 2027, the employer affordability percentage is 10.22%.
Example
For example: Bob is married with two children, and they have a household income of $51,150 (155% FPL). The family has the opportunity to enroll in group coverage through Bob’s job. Bob’s self-only coverage from his employer costs $1,535 annually, or 3% of the household income, so he is ineligible for Marketplace financial assistance. Family coverage costs $15,345 annually, or 30% of the household income. Since the cost of employer coverage for the family exceeds the affordability threshold of 10.22%, Bob’s family may be eligible for financial assistance to obtain Marketplace coverage.
Curious about your health insurance cost? Click here
Health insurance that fits your life
ThruCore will guide you through finding quality health insurance that suits your needs, at no cost to you.
Qualifying for coverage is only one part of the equation; understanding how to use your benefits is the other. We don’t just show you what to do, we teach you so you can do it yourself.
WHEN CAN I APPLY?
OPEN ENROLLMENT for private insurance sold off the Marketplace exchange and on the Marketplace exchange follow the AFFORDABLE CARE ACT guidelines.
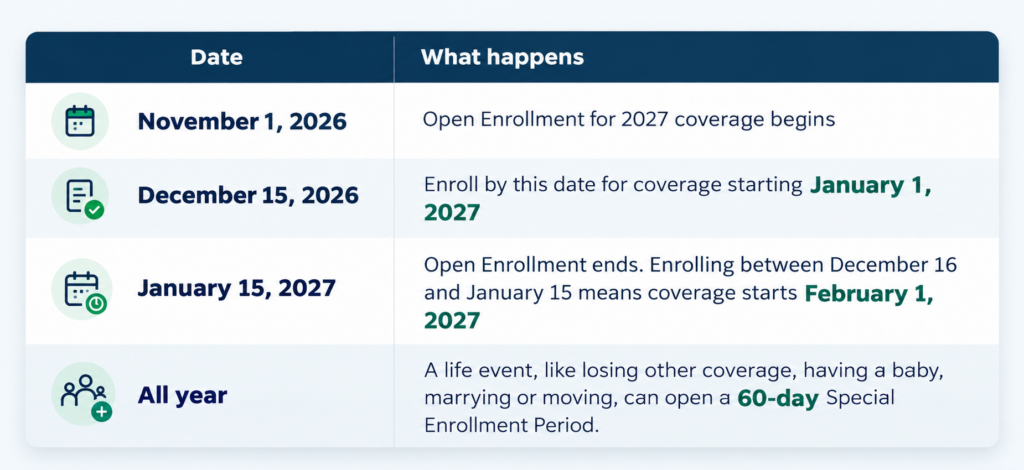
When Open Enrollment is closed, they are open to individuals experiencing special circumstances that allows them access to coverage example loss of coverage within a two month period. (grid below explains under the All Year section)
Dates for Open Enrollment
WHAT ARE MY OPTIONS?
If you don’t have health insurance through an employer, you have two main paths:
- The Health Insurance Marketplace: plans where you may qualify for help lowering your monthly premium, based on your household income and size.
- Plans sold directly by insurance companies: you pay the full premium, with no financial help.
What will my health insurance cost?
Help paying your premium depends on your household income compared to the federal poverty guidelines. For 2027 coverage, the Marketplace uses the 2026 guidelines below (48 contiguous states, including Florida).
Household Income Guidelines
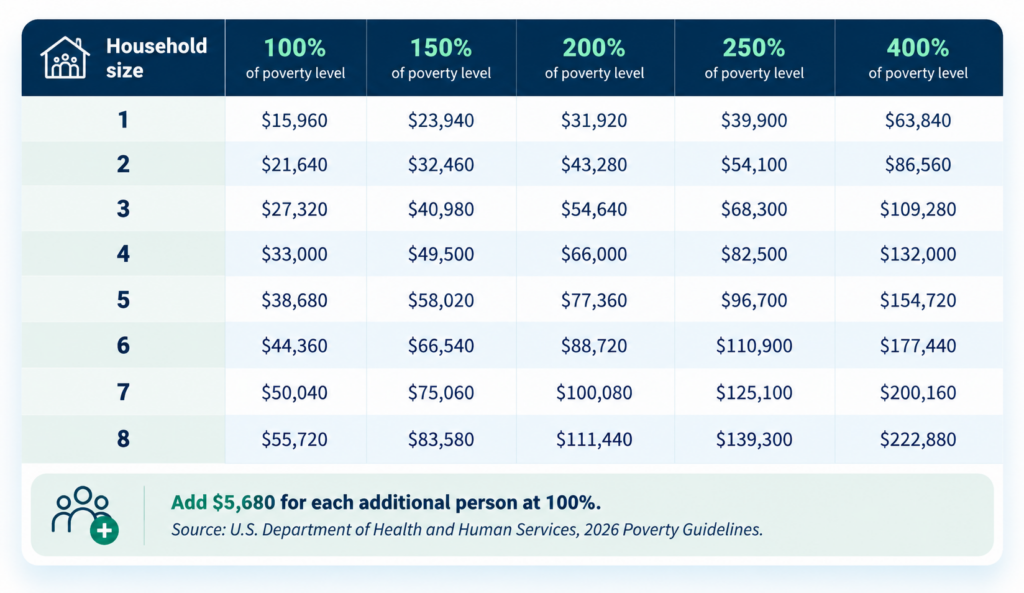
Source: U.S. Department of Health and Human Services, 2026 Poverty Guidelines.
In general:
Premium help is available for household incomes between 100% and 400% of these amounts. The extra help available from 2021 to 2025 has ended, so above 400% there’s no premium help. Lower incomes, especially up to 250%, may also qualify for lower deductibles and copays on Silver plans.
Florida has not expanded Medicaid, so many adults below 100% don’t qualify for either program; call us to review your options.
2027 change for some immigrants:
Premium help is now limited to U.S. citizens, green card holders, Cuban and Haitian entrants, and certain Compact of Free Association migrants.
Call us to review your household.
Top questions we answer
Trying to understand all the moving parts of health insurance can be very frustrating and confusing at the same time.
Call us for the right answers.
- What is a subsidy, and do I qualify?
- What are the benefits?
- Can I keep my doctor?
- What’s the difference between Bronze, Silver, Gold and Platinum?
- What are deductibles, coinsurance, copays and out-of-pocket maximums?
- Is the lowest premium always the best choice?
- What do I need to report at tax time?
ThruCore Solutions is a licensed insurance agency. We are not HealthCare.gov and are not connected with or endorsed by the U.S. government. General education, not advice for your situation. Eligibility and costs are determined by the Marketplace.